1. The dam finally breaking in Japan
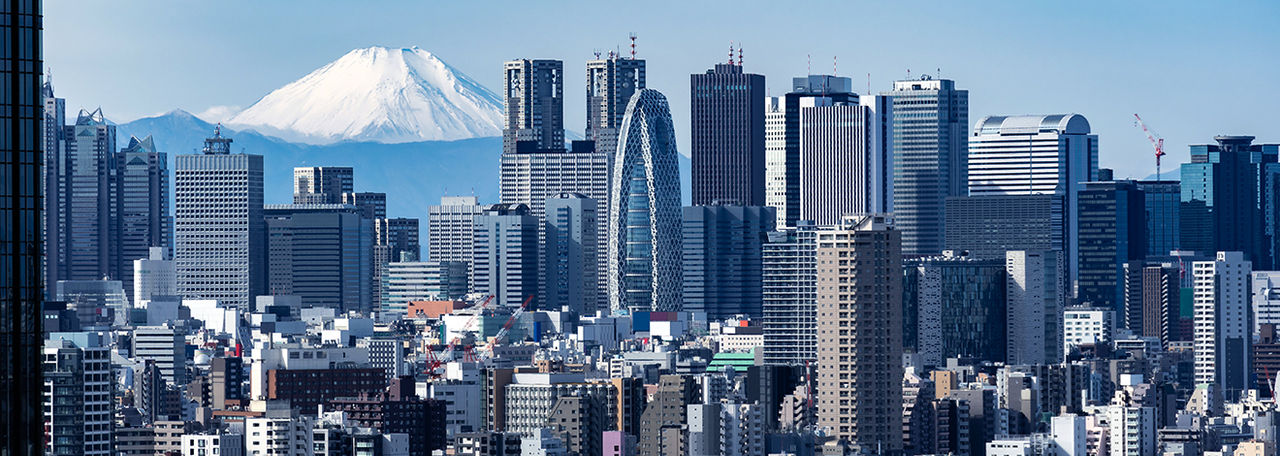
It took six years from the exploration tour before KKR completed its first (small) corporate carve-out in Japan, and another three years for its first major one, Panasonic’s health care division. Deal activity gained momentum over the next decade, but only really reached escape velocity following two landmark reforms in 2023: Tokyo Stock Exchange rules pressuring companies to address their cost of capital and low valuations, and government takeover guidelines making it harder for boards to dismiss bona fide acquisition offers.
Japanese buyout and exit value nearly tripled between 2022 and 2025 to a record US$92.5B.1 That was also the first year when more Japanese companies were taken private than went public.
“The Japanese corporates are not looking for cheap money,” said Hirano. “They’re looking for the right solutions — how the provider can help make the right acquisition outside the country or help with post-merger integration.”
Governance reform is only one driver. Some 90% of Japan’s small and medium-sized companies are family-owned. In a rapidly aging society, this has created a “succession cliff,” with succession-driven deals now accounting for two-thirds of Japanese buyouts.2
Demographics are also accelerating Japan’s embrace of automation. Where other countries worry about AI displacing workers, Japan sees it as a solution to a chronic labor shortage. But the automated society policymakers envision will require far more compute and power. The government estimates electricity output must rise 35%-50% by 2050, reversing two decades of stagnant demand.3
2. The sheer scale of Asia’s AI infrastructure needs
Japan is only one manifestation of a vastly larger Asian infrastructure problem. Szlezak put the scale of the mismatch — and the resulting investment opportunity — in stark perspective.
The U.S. attracts approximately two thirds of global data center investment, leaving the remaining third roughly split between Asia ex-China and Europe.4 Excluding China, all of Asia attracts investment comparable to Northern Virginia’s data center belt.5
At the same time, Asia accounts for 60% of the world’s internet traffic6, has more than four times the combined population of the U.S. and Europe7, and a GDP growing two to three times faster.8
Current compute capacity tells the story: 160 watts per capita in the U.S., 50 in Europe, and just six in Asia.9
Closing that gap requires more than data centers. AI needs power, transmission, cooling, and related infrastructure. And as AI becomes increasingly intertwined with national security, Szlezak expects countries to prioritize domestic capacity — perhaps eventually treating it as a strategic reserve much like oil.
Greater efficiency is unlikely to dent the need for investment. The cost of producing an AI token has fallen 99% over the past four years10, yet cheaper compute has so far fueled dramatically higher consumption.
Estimates vary widely, but PwC projects that Asia-Pacific alone could require US$8.2 trillion in AI infrastructure investment through 2050 — roughly a quarter of the global total.11 Where will all that capital come from?
3. Asia starts to bank on private credit
Asia has historically relied primarily on banks for credit. They still provide 88% of the region’s credit capital, compared with 50% in Europe and just 31% in the U.S. But the forces reshaping Japan and driving AI infrastructure investment are testing that model.12
Asia already has roughly US$3.8 trillion in private equity — nearly twice Europe’s total — but less than US$90 billion in private credit. Applying Europe’s debt-to-equity mix would imply roughly US$900 billion of additional private-credit opportunity from sponsor-backed companies alone.13
This isn’t about replacing banks. Unlike in the U.S. and Europe, regulators aren’t forcing Asian banks to retrench. Instead, private credit is emerging as a complementary source of flexible capital alongside institutions deeply embedded in corporate financing.
Broadly speaking, Raposio explained, Asian banks offered “very, very cheap capital, but usually in a very rigid and inflexible way.” Corporates, particularly those seeking to retain more equity, are turning to private credit to plug the gap.
And on AI, she added, “We’re even being told by the banks in Japan, ‘We can’t finance all of this. We need other forms of capital’” to support data center and energy investment.
Very, Very Essential
Capturing an opportunity of this scale will require discipline and the right capabilities. Szlezak emphasized the importance of drawing on experience from previous technology cycles, assessing the staying power of customers and leveraging strategic partnerships. In credit, Raposio pointed to selective underwriting, thoughtful portfolio construction and structures designed to protect capital, while Hirano highlighted the importance of aligning management and employees to “think like an owner, act like an owner.”
Together, these approaches reflect the increasingly important role private capital can play in Asia’s transformation. As Patel summed up the discussion, private capital in Asia has gone from “complementary to very, very essential.”